The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Public liability insurance is a critical form of coverage that protects businesses against claims of injury or damage caused by their operations to members of the public. Its primary purpose is to cover legal costs and compensation payments, which can otherwise cripple a business financially.
Understanding the importance of public liability insurance is essential for effective business risk management. It offers a safety net that safeguards a business's assets and ensures that unforeseen events do not devastate a company's future. Without it, businesses expose themselves to significant financial risk from potential legal claims.
This article is targeted at Australian businesses, aiming to raise awareness about public liability insurance and the common risks associated with it that many may overlook. We'll explore various aspects crucial to protecting your business, helping you identify, understand, and manage public liability risks effectively.
Slip and Fall Hazards
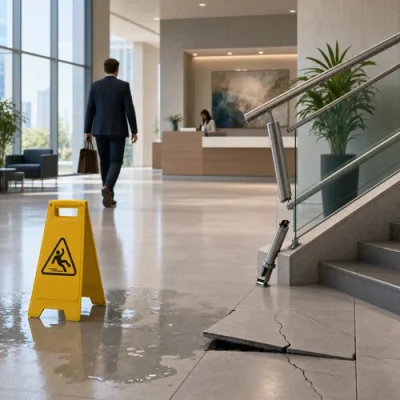
Slip and fall accidents are among the most common public liability risks businesses face. These accidents can occur in any setting, from retail stores to office spaces, and often lead to costly legal claims and compensation payouts. The impact of something as simple as a wet floor or uneven surface can be surprisingly significant, making it crucial for business owners to pay attention to potential hazards.
Poor maintenance is a key contributor to these risks. Worn carpets, loose floor tiles, and inadequate lighting can all increase the likelihood of someone slipping, tripping, or falling. When maintenance is neglected, the risk of accidents rises dramatically, putting businesses in a vulnerable position regarding liability claims.
Preventive measures are vital in reducing the incidence of slip and fall accidents. Regular inspections and maintenance of premises, ensuring proper signage for wet floors, and implementing non-slip flooring in key areas can make a substantial difference. Additionally, training staff to promptly address hazards, such as spills or debris, adds another layer of protection. By proactively managing these risks, businesses can significantly lower their exposure to slip and fall claims, safeguarding both finances and reputation.
Customer Injury from Products
Product liability is an essential aspect of public liability risk management, ensuring that businesses are accountable for any harm caused by their products. When customers suffer injuries due to defective goods, businesses may face significant lawsuits and compensation claims. Unlike other liability risks, product liability isn't confined to a particular location. The responsibility extends wherever the products are distributed or sold.
Common examples of products that could cause harm include faulty electrical appliances, harmful cosmetics, and defective children's toys. Even seemingly benign items like food products can pose a risk if they contain allergens that aren't properly disclosed. It's crucial for businesses to understand these risks, as a single incident involving a hazardous product might lead to a ripple effect of negative publicity and financial setbacks.
To ensure product safety and compliance, businesses must adopt stringent quality control processes. Regular testing and evaluation can help identify potential hazards before products reach consumers. Compliance with industry standards and regulations is also critical. Maintaining thorough documentation for all safety checks and modifications provides additional protection, should any issues arise. By prioritizing safety, businesses not only protect their customers but also enhance their reputation and reduce their vulnerability to public liability claims.
Errors in Professional Services
Professional liability is a crucial consideration for businesses providing services that require a high degree of skill or expertise. Unlike physical accidents, errors in professional judgment or service can lead to complex public liability claims. This type of risk primarily concerns any mistakes or negligence that cause clients to suffer financial loss or damage, putting the service provider in a precarious legal position.
Errors in professional services can range from simple misunderstandings or incorrect advice to significant oversights that lead to catastrophic results. Industries such as consulting, healthcare, and legal services are particularly vulnerable, as the potential for errors in these fields carries immense financial and reputational risks. When these errors occur, clients may seek compensation, leading to lawsuits that could be costly and damaging to your business's credibility.
To mitigate risks associated with professional service errors, implementing strong best practices is essential. These include maintaining clear and open communication with clients, accurately documenting all interactions, and setting realistic expectations for the services provided. Regular training and up-to-date knowledge of industry standards can further reduce the likelihood of errors. Additionally, professional liability insurance can offer a valuable safety net, providing coverage against claims arising from such mistakes, ultimately protecting your business's bottom line and reputation.
Third-party Injuries on Property
Third-party injuries on a business's property are a common concern for public liability. These injuries can occur when visitors, customers, or even passersby suffer harm due to conditions present on the property. The types of injuries can vary widely, ranging from minor cuts and bruises to more serious incidents like broken bones or concussions.
Several factors can contribute to third-party injuries on a property. Poorly maintained areas, such as cracked pavements or loose railings, are common culprits. Additionally, inadequate lighting can lead to trip hazards, while blocked emergency exits can amplify the risk during emergency situations. These situations highlight the importance of maintaining a safe environment for all individuals who interact with your business premises.
To reduce the likelihood of incidents, proactive measures are essential. Regularly inspect your property to identify and rectify potential hazards promptly. Ensure that walkways and emergency exits are clear and well-lit, and consider installing safety features like handrails where necessary. Growing a culture of safety within your business and training staff to be vigilant about reporting and addressing potential issues immediately can significantly reduce the risk of accidents, protecting both your visitors and your business from potential liability claims.
Cyber Liability Issues
As the business world becomes increasingly digital, the relevance of cyber liability has never been more pronounced. Cyber liability refers to the risks associated with data breaches and other digital security threats that can lead to public liability claims. With more businesses relying on online operations and storing sensitive data electronically, the potential for cyber-attacks and subsequent liability is growing at an alarming rate.
There are numerous public liability risks tied to digital interactions. Data breaches that leak customer information or hacking incidents that disable business operations are common examples. These incidents not only pose significant financial threats due to potential lawsuits but can also damage a business’s reputation, leading to a loss of trust among clients and customers.
Safeguarding against these threats requires a multifaceted approach. Implementing robust cybersecurity measures, such as firewalls, encryption, and secure authentication processes, is essential. It’s also crucial to regularly update and patch software to protect against vulnerabilities. Training employees on best practices for data protection and recognizing phishing attempts can further bolster your defense. By proactively addressing cyber liability risks, businesses can reduce the likelihood of data breaches and protect themselves from potential claims, ensuring both their financial stability and the trust of their clientele remain intact.
Navigating Public Liability Insurance
Understanding the coverage offered by public liability insurance is essential for safeguarding your business. Public liability insurance typically covers the legal costs and compensation claims associated with incidents where your business activities have caused injury or property damage to third parties. This includes accidents, injuries, and property damage that occur on your business premises or result from your business operations.
The key to effective coverage is determining the right level of insurance that matches your business's specific risk profile. Consider factors such as the size of your business, the industry you operate in, and the potential hazards your business is exposed to. These elements will help assess the coverage limits you require to ensure comprehensive protection.
Choosing an appropriate insurance provider is another crucial step. Look for insurers with strong reputations and experience in covering businesses similar to yours. It's beneficial to compare quotes and policies from multiple providers to find the best value for your needs. Consult with brokers or industry professionals who can provide insights into the nuances of different policies. By carefully selecting your insurance provider and policy, you ensure that your business is shielded from unexpected liabilities that could otherwise jeopardize its financial health.
Conclusion
Throughout this article, we've explored several critical aspects of public liability risks and the importance of securing appropriate insurance coverage to protect your business. From common incidents like slip and fall accidents and product liabilities to more specific concerns such as cyber risks and errors in professional services, understanding these risks is paramount for maintaining your business's financial health and reputation.
Effective risk management is not just about having the right insurance but also involves proactive efforts to identify, assess, and address potential liabilities continuously. By implementing robust safety measures, maintaining stringent compliance standards, and fostering a culture of awareness among your staff, you can significantly reduce the likelihood of incidents that may lead to public liability claims.
Finally, we encourage all businesses to regularly review and update their insurance policies and risk management strategies. As your business evolves, so too should your approach to managing potential liabilities. By staying informed and proactive, you can ensure your business remains resilient and well-protected against unforeseen challenges that may arise.
Published: Sunday, 23rd Mar 2025
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.