The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Public liability insurance is not automatically compulsory for every Australian business, but it may be required by law, licence conditions, contracts, venues, landlords or clients. This guide explains the difference between legal obligations, contractual requirements and practical expectations.
If you run a business in Australia, you may have been asked for public liability insurance before signing a lease, starting work on site, booking a market stall or applying for a permit. That can make it feel compulsory - but the answer is more nuanced.
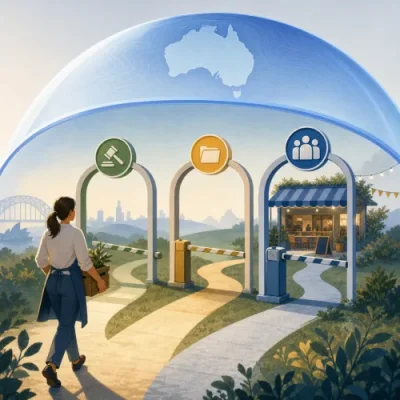
Public liability insurance is not automatically required by law for every Australian business. However, it can be legally required in some situations, contractually required in many others, and commonly expected in industries where your business interacts with customers, clients, suppliers, contractors or members of the public.
This article explains when public liability insurance may be compulsory, when it is required by contract, and when it is not legally mandatory but still an important risk-management consideration.
What does public liability insurance usually cover?
Public liability insurance is designed to help protect a business if a third party alleges they suffered injury, death or property damage because of the business's activities. Depending on the policy, it may help with legal defence costs, settlement costs or compensation payments arising from covered claims.
For example, a claim could arise if a customer slips at your premises, a contractor damages someone else's property while working, or a member of the public is injured at an event your business is involved in. The exact cover depends on the insurer, policy wording, exclusions, limits and circumstances of the claim.
Public liability insurance is different from other forms of business insurance, such as workers compensation, professional indemnity, product liability, commercial motor insurance or business property insurance. Some of those may have separate legal or contractual requirements.
So, is public liability insurance compulsory in Australia?
For most businesses, there is no single Australia-wide rule that says every business must hold public liability insurance. Unlike some forms of insurance, public liability cover is generally not automatically compulsory simply because you have an ABN, operate as a sole trader or run a small business.
However, that does not mean it is optional in every practical sense. Public liability insurance requirements can arise from several sources, including:
- Legislation or regulations affecting a specific industry, licence, permit or activity.
- Government, council or venue conditions before you can operate in a particular location or hold an event.
- Client, principal contractor or supplier agreements requiring evidence of cover before work starts.
- Commercial leases or property access agreements set by landlords or property managers.
- Industry expectations where customers or business partners expect proof of insurance as part of due diligence.
In other words, public liability insurance may not be universally compulsory, but it can still be required for your business to legally operate in a particular setting, meet contractual obligations or win certain work.
When public liability insurance may be legally required
Public liability insurance can become a legal or regulatory requirement where a law, licence, permit or authority condition requires it. These requirements can vary by state or territory, local council, industry and activity.
Common situations where a legal or regulatory requirement may arise include:
- Events held in public spaces: Councils or government authorities may require organisers, stallholders or contractors to provide evidence of public liability insurance before approving use of parks, roads, halls or other public facilities.
- Market stalls and pop-up businesses: Market operators or local authorities may require stallholders to hold public liability cover as part of participation conditions.
- Licensed or regulated activities: Some licences, permits or approvals may require evidence of insurance, especially where the activity involves public safety risks or access to public places.
- High-risk work environments: Certain sectors, such as construction, maintenance, facilities management and outdoor services, may face insurance requirements through site access rules, permits or regulatory obligations.
- Government or council contracts: Public sector tender and contract conditions often require specified insurance types and minimum limits before a supplier can commence work.
Because requirements differ across Australia, it is important to check the specific rules that apply to your activity, location and business structure. A requirement imposed by a council, licensing body or contract should not be assumed to apply everywhere else.
When public liability insurance is contractually required
Many Australian businesses first encounter public liability insurance requirements through contracts rather than legislation. A contract can require you to hold insurance even where the law does not automatically make it compulsory.
Contractual requirements are common in arrangements such as:
- commercial leases for shops, offices, workshops, clinics, warehouses or studios;
- subcontractor agreements on construction, trade, maintenance or installation projects;
- service agreements with corporate, government or not-for-profit clients;
- venue hire agreements for events, exhibitions, workshops or performances;
- supplier agreements for businesses entering another party's premises;
- franchise, licence or distribution agreements;
- labour hire, facilities management or cleaning contracts.
These contracts may specify the type of insurance required, the minimum limit of cover, whether the other party must be noted on the policy, and how often you must provide a certificate of currency. If you sign a contract requiring public liability insurance and do not maintain it, you may breach the agreement and risk losing access, work or payment.
When public liability insurance is commonly expected
Even where no law or contract requires it, public liability insurance is often expected as part of operating a responsible business. This is especially true if your work involves physical premises, visitors, customers, suppliers, contractors or work at other people's sites.
Public liability cover is commonly expected for:
- tradies and contractors who work in homes, businesses, construction sites or public areas;
- retailers and hospitality businesses with customer foot traffic;
- health, fitness and wellbeing businesses where clients attend sessions or facilities;
- event organisers, entertainers and stallholders operating in venues or public spaces;
- cleaners, gardeners and mobile service providers working at client premises;
- consultants and professional service providers who visit client sites or host visitors at their own premises;
- manufacturers, wholesalers and distributors with visitors, deliveries or premises-related risks.
For some businesses, not having public liability insurance may make it difficult to secure clients, access sites or be accepted by landlords, event organisers or tender panels. It may also leave the business exposed to legal costs or compensation claims if an incident occurs and the claim is not otherwise covered.
Legal requirement vs contractual requirement vs practical expectation
It helps to separate the different types of public liability insurance requirements. They are often discussed together, but they are not the same thing.
| Type of requirement | What it means | Common examples |
|---|
| Legal or regulatory requirement | A law, licence, permit or authority condition requires you to hold cover. | Council event permits, regulated activities, public space approvals or government contract conditions. |
| Contractual requirement | A contract says you must hold public liability insurance to perform work, access premises or lease property. | Subcontractor agreements, commercial leases, venue hire contracts and client supplier agreements. |
| Practical expectation | Insurance is not strictly mandatory, but clients, venues or industry participants expect it as part of risk management. | Tradies, mobile services, retail stores, events, hospitality venues and contractors working around the public. |
If you are unsure which category applies, review the written requirement carefully. The source of the requirement affects how strict it is, who enforces it and what evidence you may need to provide.
Examples of businesses that may be asked for public liability insurance
The following examples show how requirements can arise in practice. They are general examples only, not rules that apply to every business or location.
Sole traders and contractors
A sole trader may not be legally required to hold public liability insurance simply because they work for themselves. However, a client, head contractor or site manager may require a certificate of currency before allowing them to start work. This is common for trades, maintenance, installation, cleaning and property services.
Event organisers and stallholders
Event organisers, food vendors, market stallholders and exhibitors are often asked to provide public liability insurance before participating in an event. The requirement may come from the venue, council, event operator or permit conditions.
Retail and hospitality businesses
A shop, cafe, restaurant or salon may be required to hold public liability insurance under its lease. Even if the lease does not require it, customer foot traffic creates a practical exposure to slip, trip, injury and property damage claims.
Construction and trade businesses
Public liability insurance is frequently required before contractors can enter worksites or tender for projects. The required cover limit may depend on the principal contractor, project type, site rules and contract terms.
Professional and consulting businesses
Consultants may think only professional indemnity insurance matters, but public liability insurance can still be relevant if they visit clients, attend worksites, host meetings or operate from premises accessed by third parties.
What evidence might you need to provide?
If public liability insurance is required, you may be asked for a certificate of currency. This is a document that confirms certain details of your policy at the time it is issued. It usually includes information such as the insured business name, policy period, insurer, policy type and limit of cover.
Before providing a certificate, check that the details match the contract or permit requirements. Common issues include:
- the insured name not matching the contracting business or ABN;
- the policy limit being lower than the required amount;
- the business activity description not matching the work being performed;
- the policy expiring before the project, lease or event ends;
- the contract requiring additional insured or interested party wording that is not automatically included.
If the certificate does not meet the requirement, you may need to ask your insurer or broker whether the policy can be adjusted. Changes are not always available and may depend on underwriting criteria.
How much public liability cover might be required?
There is no single cover amount that suits every Australian business. Required limits can vary depending on the contract, council, venue, landlord, industry, project value, perceived risk and the party requesting insurance.
Some organisations specify a minimum level of cover. Others leave it to the business to decide what is appropriate. When assessing cover, consider factors such as:
- where your business operates and who may be exposed to risk;
- whether you work in public places, client premises or high-traffic environments;
- the potential severity of injury or property damage claims;
- contractual minimum limits and tender requirements;
- the type of clients, venues or sites you work with;
- policy exclusions, excesses and conditions, not just the headline limit.
For a deeper discussion on limits and risk factors, see our guide to calculating adequate public liability coverage.
What happens if you do not have required public liability insurance?
The consequences depend on why the insurance was required. If it was a legal, permit or licence requirement, you may be unable to lawfully operate in that setting or may risk penalties, cancellation of approval or enforcement action. If it was a contractual requirement, you may breach the contract, lose access to a site, be removed from a supplier panel, or be unable to start or continue work.
There is also the financial risk. If an uninsured business faces a third-party injury or property damage claim, it may need to fund legal advice, defence costs, settlements or court-ordered compensation itself. The actual outcome depends on the facts, legal liability and available defences.
Insurance does not remove the need for safe systems of work, proper maintenance, staff training or compliance with workplace and consumer obligations. It is one part of a broader risk-management approach.
How to check your public liability insurance requirements
If you are not sure whether public liability insurance is compulsory for your business, take a structured approach.
- Check your contracts. Review leases, client agreements, subcontractor terms, tender documents, supplier agreements and venue hire conditions.
- Check permit and licence conditions. Look at council approvals, event permits, industry licences and any conditions attached to public space use.
- Ask the party requesting insurance. Confirm the required policy type, limit, insured name, certificate wording and dates in writing.
- Consider your actual risk exposure. Think about who could be injured or whose property could be damaged because of your operations.
- Compare policy wording carefully. Look beyond the premium and check inclusions, exclusions, excesses, policy limits and business activity descriptions.
- Get general assistance if needed. If the requirement is complex, consider speaking with an insurance broker, solicitor or relevant industry body.
You can also review available public liability insurance quotes to understand the types of information insurers may ask for. Policy availability, pricing and terms depend on the business, risk profile and insurer criteria.
Questions to ask before buying or renewing cover
Before arranging or renewing public liability insurance, it can help to ask:
- Does my lease, contract, permit or licence require public liability insurance?
- What minimum limit of cover is required?
- Does the policy need to name or note another party?
- Are my business activities accurately described?
- Do I work away from my premises, at events, on worksites or in public places?
- Are subcontractors, temporary workers or stallholders relevant to my risk?
- Are there exclusions that could affect my work?
- How quickly can I obtain an updated certificate of currency if needed?
If you need help understanding policy obligations or comparing options, you may wish to speak with a broker. Any insurance decision should be based on your own business circumstances, contract terms and risk profile.
Key takeaways
- Public liability insurance is not automatically compulsory for every Australian business.
- It may be legally required for certain licences, permits, public space use, events or regulated activities.
- It is often required by contracts, leases, tenders, venues, landlords, councils or principal contractors.
- Even when not mandatory, it is commonly expected for businesses that interact with customers, clients, suppliers or the public.
- Always check the exact wording of your contract, permit or licence before assuming what cover is required.
- Policy terms, limits, exclusions, availability and pricing vary by insurer and individual business circumstances.
Public liability insurance requirements in Australia are best understood as a mix of legal obligations, contractual conditions and practical business expectations. If someone asks you for proof of cover, find out who is asking, why they need it, what limit they require and whether the policy wording aligns with your actual business activities.
Published: Wednesday, 5th Aug 2026
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.